EV Insurance Guide
Tesla Roadster
Tesla Roadster insurance considerations for the original 2008-2012 electric sports car, including battery coverage, specialized repairs, replacement parts, and collector-car valuation.
Overview
The original Tesla Roadster is a two-seat, all-electric sports car produced for model years 2008 through 2012. Based on a modified Lotus Elise-derived chassis, it was Tesla's first production vehicle and helped demonstrate the potential of lithium-ion battery technology in a high-performance electric car.
Unlike modern Tesla vehicles, the original Roadster was produced in relatively small numbers and uses early-generation electric vehicle technology. Its lightweight construction, removable roof, compact sports-car design, and specialized electrical components create distinctive ownership and insurance considerations.
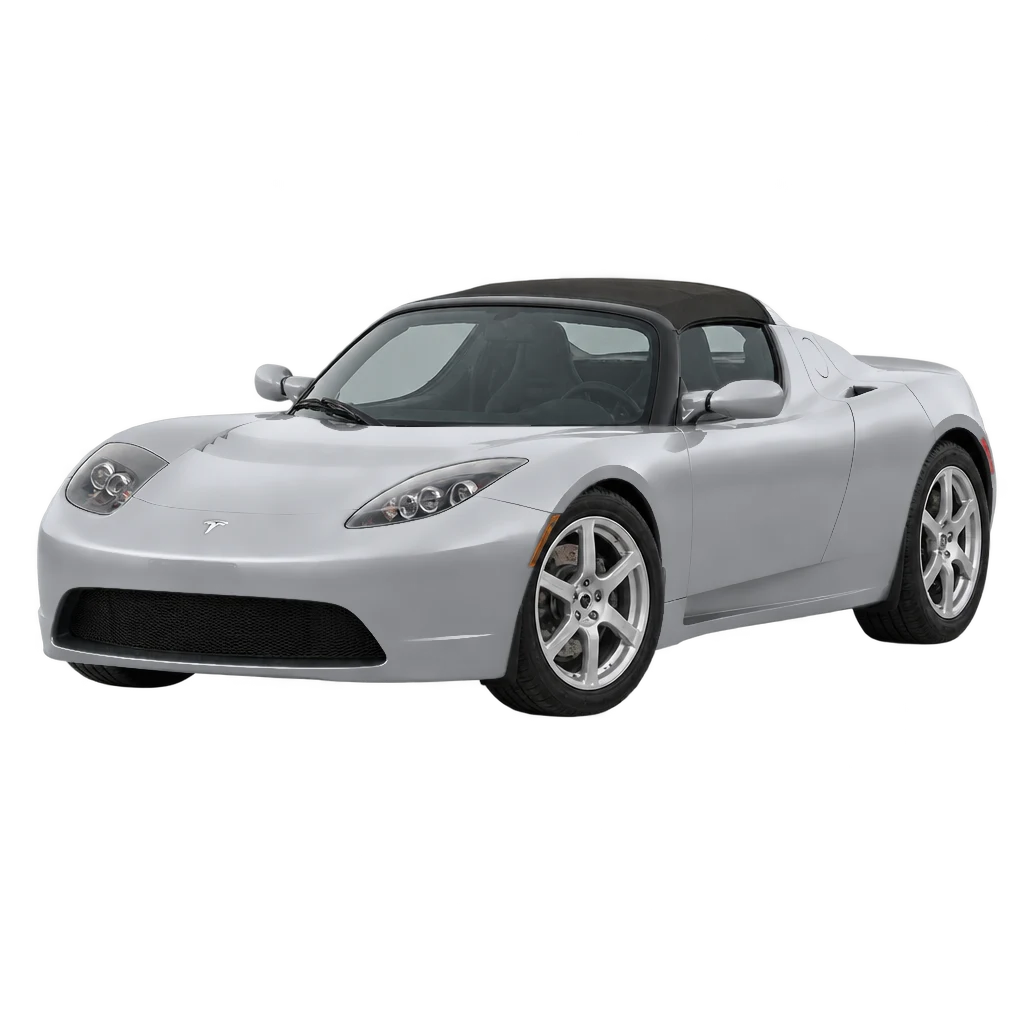
Roadster versions included the original Roadster and the higher-performance Roadster Sport. Equipment, specifications, and condition vary between individual vehicles, and modifications or upgrades may affect valuation and repair requirements.
Insurance considerations include limited replacement-parts availability, specialized repair expertise, battery condition, vehicle age, and the possibility that an individual Roadster's market value may differ from conventional depreciation-based estimates.
This guide focuses exclusively on the original production Roadster. Any proposed next-generation Tesla Roadster is a separate vehicle and is not covered here.
How Much Does Tesla Roadster Insurance Cost?
Tesla Roadster insurance premiums depend on the individual vehicle's value, condition, driver, location, annual mileage, intended use, coverage, deductibles, and insurer. Because the original Roadster was produced in limited numbers, insurers may have fewer directly comparable vehicles and repair claims than they do for mass-market cars. Its specialized components and limited replacement-parts availability can also complicate damage estimates. Vehicle condition and value are particularly important. A well-preserved, low-mileage Roadster may have a different market value from a heavily used or modified example. Roadster Sport models and vehicles with documented upgrades may also require careful valuation. Some owners may qualify for collector or specialty vehicle insurance, depending on the insurer's requirements for vehicle use, storage, mileage, condition, and other factors. These policies may offer agreed-value options but can include restrictions that differ from standard auto insurance. There is no single insurance premium that accurately represents every original Tesla Roadster. Compare personalized quotes using the exact VIN, model year, condition, documented equipment, estimated value, annual mileage, and intended use.
What affects insurance cost
Several factors specific to the Tesla Roadster are worth understanding when shopping for insurance.
Limited Production and Vehicle Value
The original Tesla Roadster was produced in relatively small numbers. Individual values may depend on condition, mileage, originality, service history, equipment, and collector demand. Insurers may need specialized valuation information rather than relying exclusively on ordinary used-car comparisons.
Battery Age and High-Voltage Components
The Roadster uses an early-generation lithium-ion battery system. Battery age, maintenance history, and component availability may influence ownership and repair considerations. Physical damage caused by an eligible insured event may be covered, while ordinary degradation and unrelated mechanical failure generally are not covered by standard auto insurance.
Limited Replacement Parts
Original Roadster-specific body, electrical, and mechanical components may be difficult to source because the vehicle is no longer in production. Parts availability, replacement options, and specialized labor can influence repair costs and claim timelines.
Lightweight Sports-Car Construction
The Roadster's Lotus-derived structure and lightweight body construction require model-appropriate repair procedures. Collision damage may involve specialized structural assessment, composite body components, and qualified repair facilities.
Roadster Sport and Vehicle Modifications
Roadster Sport versions and vehicles with aftermarket modifications or documented upgrades may have different values and repair requirements. Owners should disclose relevant modifications and confirm how their insurer evaluates additional equipment and replacement costs.
Collector Insurance and Driving Restrictions
Some Roadster owners may qualify for specialty or collector-car insurance with agreed-value options. Eligibility can depend on annual mileage, storage, vehicle condition, and permitted use. Owners should compare policy restrictions carefully before choosing collector coverage instead of standard auto insurance.
Battery and insurance
The original Tesla Roadster uses a lithium-ion battery system developed during an early period of modern electric vehicle production. Battery condition and service history are important considerations because the vehicle is now more than a decade old. Collision insurance may cover physical battery damage caused by an eligible accident. Comprehensive coverage may apply to qualifying non-collision events, such as certain fires, flooding, or other covered perils. Coverage depends on policy terms, exclusions, deductibles, and the circumstances of the claim. Ordinary battery aging, gradual capacity loss, and mechanical or electrical failure without a covered cause generally fall outside standard auto insurance coverage. Any applicable battery warranty or service arrangement is separate from an insurance policy. Battery replacement or repair may involve specialized components and limited service options. Owners should ask how their insurer evaluates battery diagnostics, replacement availability, labor costs, and repair feasibility following a covered loss. Battery condition may also influence the vehicle's market value, making accurate documentation useful when arranging coverage or reviewing a total-loss settlement.
Repair considerations
The original Tesla Roadster combines a modified Lotus-derived chassis, lightweight body construction, specialized electric drivetrain components, and early-generation Tesla electronics. Collision repairs may require expertise with composite body panels, structural components, and the Roadster's high-voltage electrical system. Not every modern Tesla repair facility or general collision shop necessarily has the equipment or experience to perform original Roadster repairs. Replacement parts may be limited because production ended in 2012. Owners should verify parts availability, repair capabilities, and insurer authorization before proceeding with specialized repairs. Repair costs and timelines depend on damage severity, component availability, and the experience of the selected facility. Some damage may be difficult or uneconomical to repair, particularly when rare parts or high-voltage components are involved. Owners should consider towing and rental reimbursement coverage where available, while recognizing that specialty or collector policies may have different transportation benefits and restrictions.
Cameras, sensors, glass and technology
The original Tesla Roadster predates the camera-based driver-assistance systems and advanced vehicle electronics found in modern Tesla models. It does not have modern Tesla Autopilot, Full Self-Driving capability, or the contemporary camera-based driver-assistance architecture used in newer Tesla vehicles. Its insurance-related technology considerations instead involve the original electric drivetrain, battery management, charging components, instrumentation, and other vehicle-specific electrical systems. Windshield, lighting, body, and electrical repairs may require model-specific parts or specialized knowledge. Owners should verify that the selected repair facility has experience with the original Roadster and can obtain the necessary components. Insurance comparisons should reflect the actual equipment and condition of the individual vehicle rather than assuming it has the safety or driver-assistance features of a modern Tesla.
Coverage considerations
Owners of the original Tesla Roadster should compare liability, collision, comprehensive, uninsured or underinsured motorist coverage, and applicable medical coverage. Requirements and availability vary by state and insurer. Collision coverage generally addresses damage from eligible accidents, while comprehensive coverage generally addresses qualifying non-collision events such as theft, fire, falling objects, and certain weather damage. Both are subject to policy terms, exclusions, and deductibles. Because the original Roadster is a limited-production vehicle with specialized components, owners should pay particular attention to vehicle valuation, replacement-parts availability, and access to qualified repair facilities. Some owners may qualify for collector or specialty insurance offering agreed-value coverage. Under an agreed-value arrangement, the insurer and owner establish an insured value in advance, subject to the policy's terms and conditions. Owners should compare this approach with standard actual cash value coverage. Collector policies may restrict annual mileage, everyday driving, storage, or other uses. The lowest premium is not necessarily the best option if the policy does not accommodate how the vehicle will actually be driven. Owners should also review coverage for documented upgrades, aftermarket equipment, towing, and transportation expenses following an eligible claim.
Deductibles
A deductible is the amount an insured owner pays toward an eligible claim before the applicable insurance payment. Collision and comprehensive coverage commonly have separate deductibles. A higher deductible may reduce premiums but increases out-of-pocket expenses after a covered loss. A lower deductible generally increases premiums while reducing the amount paid toward an eligible claim. For the original Tesla Roadster, consider the potential cost and availability of specialized body panels, glass, electrical components, and high-voltage repairs when selecting deductibles. Collector and specialty policies may offer different deductible structures or coverage conditions from standard auto policies. Owners should compare the actual terms rather than assuming all policies provide equivalent protection. Compare quotes using equivalent coverage limits, deductibles, valuation methods, and permitted driving arrangements.
Accidents and total loss
An original Tesla Roadster may be declared a total loss when repair costs meet applicable insurer and state-law criteria relative to the vehicle's value. Total-loss rules and settlement methods vary by jurisdiction and policy. Under standard actual cash value coverage, the insurer generally considers the vehicle's age, condition, mileage, equipment, and comparable market values. Limited production and collector demand can make accurate comparisons more challenging than for common vehicles. Roadster Sport versions, documented upgrades, originality, service history, and battery condition may influence the vehicle's market value. Specialized body repairs, limited replacement-parts availability, and high-voltage component damage may also affect repair estimates and total-loss decisions. However, damage to an expensive component does not automatically mean the vehicle must be declared a total loss. An agreed-value collector policy may provide a more predictable insured value for a covered total loss, subject to its terms, exclusions, and any applicable deductible. Owners should maintain photographs, service records, documentation of upgrades, and relevant valuation information. These records may help establish appropriate coverage and support a claim.
Questions to ask an insurer
Can you insure my original 2008-2012 Tesla Roadster under a collector or specialty policy, and what driving, mileage, and storage restrictions apply?
Do you offer agreed-value coverage for the original Roadster, and how does it differ from your standard actual cash value settlement?
Does your policy cover physical damage to the Roadster's high-voltage battery from an eligible collision or comprehensive claim?
Can I use a qualified repair facility experienced with original Tesla Roadsters, including their specialized body construction and electrical systems?
How does your policy handle limited replacement-parts availability, specialized labor, and repairs involving rare Roadster-specific components?
How are Roadster Sport equipment, documented upgrades, aftermarket modifications, and vehicle condition reflected in the insured value?
What towing, transportation, and rental reimbursement benefits are available, and do they differ under a collector or specialty policy?
Ways to shop smarter
Compare standard auto insurance with collector or specialty policies if your original Roadster meets the applicable eligibility requirements.
Ask whether agreed-value coverage is available and understand how it differs from actual cash value when settling a covered total loss.
Obtain quotes using the exact VIN, model year, Roadster or Roadster Sport configuration, vehicle condition, annual mileage, and intended use.
Document service history, battery condition, originality, upgrades, and recent photographs to help support an accurate insured value.
Confirm that your preferred repair facility has experience with the original Roadster and can obtain necessary replacement parts.
Review coverage for eligible high-voltage battery damage while recognizing that ordinary aging and mechanical failure generally are not covered by auto insurance.
Compare deductibles, towing benefits, storage requirements, mileage restrictions, and permitted driving activities before selecting a collector policy.
Review the vehicle's insured value at renewal, especially after significant repairs, documented upgrades, or changes in collector-market conditions.
Frequently asked questions
Is the original Tesla Roadster expensive to insure?
Insurance premiums depend on the vehicle's value, condition, driver, location, annual mileage, coverage, deductibles, and insurer. Limited production, specialized repairs, and replacement-parts availability can influence claim costs. Some owners may qualify for collector insurance, but eligibility and driving restrictions vary. Compare personalized quotes rather than relying on a single average premium.
Can I get collector-car insurance for a 2008-2012 Tesla Roadster?
Some specialty insurers may consider the original Roadster for collector coverage, depending on its condition, value, storage, annual mileage, and intended use. Policies may offer agreed-value protection but restrict everyday driving or other activities. Eligibility and terms vary by insurer, so confirm that the policy accommodates how you actually use the vehicle.
What is agreed-value insurance for a Tesla Roadster?
Agreed-value insurance generally establishes an insured vehicle value between the owner and insurer before a loss. For a covered total loss, the policy may pay the agreed amount subject to its terms, exclusions, and any applicable deductible. This differs from standard actual cash value coverage, which generally uses the vehicle's value immediately before the loss.
Does insurance cover the original Tesla Roadster battery?
Physical battery damage caused by an eligible collision or comprehensive event may be covered, subject to policy terms and deductibles. Ordinary battery degradation, gradual capacity loss, and mechanical or electrical failure without a covered cause generally are not covered by standard auto insurance. Battery condition and replacement availability can also affect repair and valuation considerations.
Are original Tesla Roadster replacement parts difficult to find?
Certain original Roadster-specific body, electrical, and mechanical parts may be difficult to obtain because the vehicle is no longer in production. Availability depends on the component and available service or parts sources. Limited supply can increase repair time or complexity. Confirm qualified repair options and parts availability before arranging coverage or authorizing repairs.
Can any Tesla service center repair the original Roadster?
Not every Tesla service location or collision facility necessarily supports the original Roadster or performs all specialized repairs. The vehicle uses older technology and unique components that require model-specific knowledge. Contact the facility directly to confirm its capabilities, parts access, and ability to perform the required work.
Is the Tesla Roadster Sport more expensive to insure?
Roadster Sport models may have different market values, performance characteristics, and equipment from other original Roadster versions. These differences can affect insurer pricing and valuation, but there is no universal premium difference. Request quotes using the exact vehicle configuration, condition, documented equipment, and intended use.
How is an original Tesla Roadster valued after a total loss?
Under standard actual cash value coverage, valuation generally considers condition, mileage, equipment, service history, and comparable market information. Limited production and collector demand may complicate comparisons. An agreed-value policy may establish a predetermined insured amount for an eligible total loss. Review the settlement method and documentation requirements before purchasing coverage.
Does this guide cover the next-generation Tesla Roadster?
No. This guide covers the original Tesla Roadster produced for model years 2008-2012. The proposed next-generation Roadster is a separate vehicle. Its final production specifications, availability, and insurance characteristics should not be assumed to match the original Roadster.
Related EV insurance topics
Ready to compare?
Compare EV insurance options and find coverage that fits your needs.