EV Insurance Guide
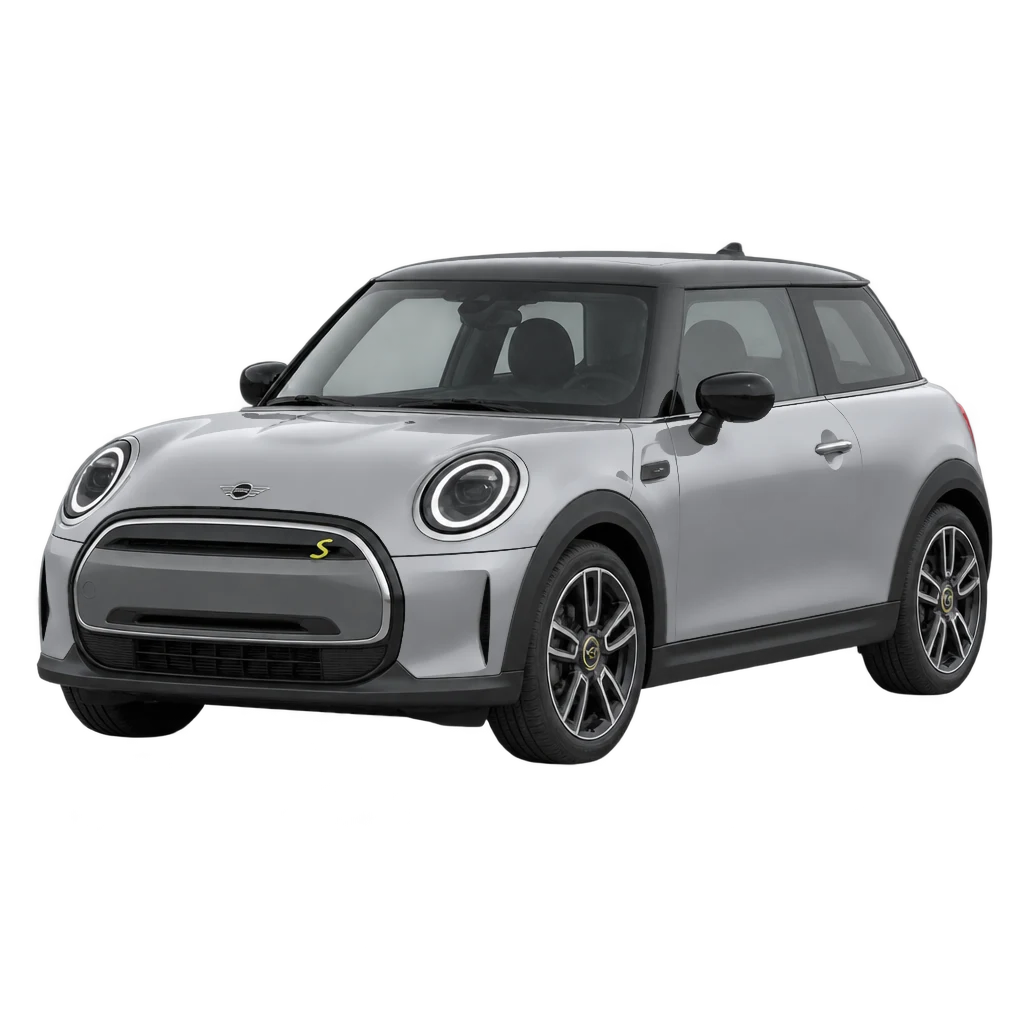
MINI Cooper SE
Insurance considerations for the MINI Cooper SE all-electric two-door hatchback.
Overview
The MINI Cooper SE is a compact, fully electric two-door hatchback that entered the United States market for the 2020 model year. Built at MINI's Oxford plant in the United Kingdom, the Cooper SE combines the familiar MINI Hardtop design with a front-wheel-drive electric powertrain. The U.S.-market electric Cooper SE was offered through the 2024 model year. Although MINI introduced a newer generation of electric Cooper models internationally, that vehicle was not part of the regular U.S. Cooper lineup for the 2025 through 2027 model years. The gasoline-powered MINI Cooper S and the larger electric Countryman SE ALL4 are different vehicles. The U.S. Cooper SE produces 181 horsepower and 199 lb-ft of torque through a single electric motor driving the front wheels. It has a 32.6 kWh gross lithium-ion battery, with approximately 28.9 kWh of usable capacity in the original technical specifications. The Cooper SE was designed primarily for city driving and shorter trips. EPA-estimated range varies by model year, with the 2020 launch documentation listing approximately 110 miles and later U.S. models, including the 2024 Cooper SE, rated at approximately 114 miles. The vehicle seats four people and retains the compact dimensions, distinctive styling, and responsive handling associated with MINI. Insurance considerations include its current market value, high-voltage battery, compact body construction, electronic systems, replacement-part availability, and the cost of specialized EV repairs.
How Much Does MINI Cooper SE Insurance Cost?
Insurance costs for a MINI Cooper SE depend on the vehicle's model year, current market value, driver profile, location, annual mileage, coverage limits, deductible, and insurance company. As a compact electric hatchback, the Cooper SE has different replacement-value and repair considerations than larger luxury electric vehicles. However, its relatively small size does not automatically guarantee inexpensive insurance. Repairs involving the high-voltage battery, electronic components, body panels, or specialized EV systems can still be costly. The Cooper SE's age and depreciation are also important considerations. A used 2020 model may have a substantially different market value than a 2024 model. Insurance companies consider the complete vehicle and driver risk profile rather than assigning one universal premium to every Cooper SE. Comparing personalized quotes from multiple insurers is the most reliable way to evaluate coverage and pricing.
What affects insurance cost
Several factors specific to the MINI Cooper SE are worth understanding when shopping for insurance.
Compact hatchback replacement value
The Cooper SE is a premium-brand compact hatchback with distinctive styling and model-specific components. Although its original purchase price was lower than that of many luxury EVs, replacement parts and manufacturer-specific repairs may still contribute to claim expenses. Insurers consider the vehicle's current value, expected repair costs, theft exposure, and other factors when determining premiums. Actual cash value generally reflects the vehicle's present market value rather than its original MSRP. Owners should compare the cost of collision and comprehensive coverage against the vehicle's current value, particularly as the vehicle depreciates.
High-voltage battery and electrical systems
The U.S. MINI Cooper SE uses a 32.6 kWh gross lithium-ion battery, with approximately 28.9 kWh usable capacity in the original technical specifications. The battery is arranged in a T-shaped configuration within the vehicle floor, helping preserve interior and luggage space. Although smaller than the batteries in many modern electric SUVs, it remains a specialized high-voltage component requiring appropriate diagnostic equipment, training, and safety procedures. After a collision, technicians may need to inspect the battery enclosure, electrical connections, cooling components, and surrounding structure. Battery damage can significantly affect repair costs, but it does not automatically mean the vehicle must be declared a total loss.
MINI-specific body panels and replacement parts
The Cooper SE shares much of its overall body design with the MINI Hardtop, but it also has EV-specific components and trim. Collision repairs may involve distinctive body panels, lighting assemblies, charging-port components, and manufacturer-specific parts. Parts availability and repair procedures can influence the final repair cost and how long the vehicle remains in the shop. Owners should confirm that their insurer's repair network can obtain the necessary parts and perform appropriate MINI repairs.
Electric motor and regenerative braking
The Cooper SE uses a single front-mounted electric motor producing 181 horsepower and 199 lb-ft of torque. Its electric drivetrain incorporates regenerative braking, which helps recover energy during deceleration. The vehicle provides selectable regenerative braking settings. Collision damage involving the motor, power electronics, electrical connections, or related components may require specialized diagnosis. Regenerative braking also operates alongside conventional friction brakes, which remain important safety and maintenance components.
Cameras, sensors, and vehicle electronics
Depending on model year and equipment, the Cooper SE may include driver-assistance features, parking sensors, cameras, digital displays, and electronic control systems. Repairs involving windshields, bumpers, cameras, sensors, or their mounting locations may require diagnostic checks or calibration when applicable. Equipment varies across model years and option packages. Owners should confirm that their insurer's repair network can perform the procedures required for their particular vehicle.
Used-vehicle age, mileage, and condition
The U.S.-market Cooper SE covered by this guide was sold from the 2020 through 2024 model years. As these vehicles age, mileage, condition, battery health, repair history, and market depreciation can become increasingly important. A lower market value may reduce the amount at risk in a total-loss claim, but it does not necessarily reduce every repair expense. Owners should periodically review deductibles, optional coverage, and the vehicle's current value.
Battery and insurance
The MINI Cooper SE uses a lithium-ion high-voltage battery mounted low in the vehicle floor. MINI's original U.S. technical specifications list a gross battery capacity of 32.6 kWh and a net capacity of approximately 28.9 kWh. The 2020 launch documentation cited approximately 110 miles of EPA-estimated range, while later U.S. models, including the 2024 Cooper SE, are associated with an EPA-estimated range of approximately 114 miles. The Cooper SE uses a J1772-compatible connector for Level 1 and Level 2 AC charging and a CCS1 connector for DC fast charging in the United States. MINI specified AC charging at up to 7.4 kW and DC fast charging at up to 50 kW. Under suitable conditions, MINI's original documentation described DC charging to approximately 80 percent in roughly 35 to 40 minutes, depending on the starting charge level and conditions. Actual charging performance depends on charger output, battery temperature, battery state of charge, and vehicle condition. The 2024 MINI U.S. warranty booklet provides high-voltage traction battery coverage against qualifying defects in materials or workmanship for 8 years or 100,000 miles, whichever occurs first, subject to warranty conditions and exclusions. Owners of earlier model years should consult the warranty booklet applicable to their vehicle. Manufacturer warranty protection and automobile insurance cover different types of risks. Qualifying manufacturing defects or battery failures may fall under warranty coverage. Physical damage to the battery resulting from a covered collision or comprehensive event may be covered under the applicable automobile insurance provisions. Normal battery aging and degradation are generally not covered automobile insurance losses.
Repair considerations
Repairing a MINI Cooper SE may require technicians trained to work with high-voltage electric vehicle systems. Following a collision, repairs may involve inspection of the battery enclosure, high-voltage cables, motor assembly, charging equipment, cooling systems, body structure, and electronic components. The vehicle's compact dimensions do not eliminate the possibility of expensive repairs. Damage involving the charging port, electrical systems, or battery protection components may require specialized procedures. Owners should confirm that their insurer provides access to repair facilities qualified to service the electric Cooper SE. Parts availability and specialized repairs can influence repair timelines. Rental reimbursement coverage may be worth considering when comparing policies.
Cameras, sensors, glass and technology
The MINI Cooper SE includes digital vehicle information displays and electronic control systems, with additional equipment varying by model year and configuration. Available features may include parking assistance equipment, cameras, and driver-assistance technology. Windshield replacement or collision repairs involving sensors or mounting locations may require calibration or diagnostic verification when applicable. Damage to the charging-port assembly, displays, and other electronic components may require model-specific replacement parts. Owners should ask whether factory-installed electronics, sensors, glass, and necessary recalibration are covered following an eligible insured event.
Coverage considerations
Collision coverage generally addresses damage to the insured vehicle resulting from a collision with another vehicle or object, subject to policy terms and deductibles. Comprehensive coverage generally addresses covered non-collision events such as theft, fire, vandalism, and certain weather-related losses. High-voltage battery damage caused by a covered event may fall under collision or comprehensive coverage depending on the circumstances. Liability insurance addresses covered bodily injury or property damage for which the insured driver is legally responsible, subject to applicable policy limits. Owners should also consider whether rental reimbursement and roadside assistance are appropriate for their needs. Coverage for portable charging cables, home charging equipment, and personal property may differ by policy. Confirm these details directly with the insurance company.
Deductibles
A deductible is the amount the policyholder must pay toward an eligible covered claim before the insurer pays the remaining covered amount. For the Cooper SE, the relationship between deductible and current vehicle value is particularly important. As a used EV depreciates, a deductible that was reasonable when the vehicle was newer may represent a larger percentage of its current market value. A higher deductible may reduce the premium but increases the owner's out-of-pocket responsibility after a covered loss. Compare the available deductible options against your financial circumstances and the vehicle's current value.
Accidents and total loss
A MINI Cooper SE may be declared a total loss when the insurer determines that the applicable total-loss criteria have been met under state law and policy provisions. The decision may consider repair expenses, actual cash value, salvage value, and applicable legal thresholds. Damage involving the high-voltage battery, electrical systems, or structural components may substantially influence repair costs. Because the U.S. Cooper SE is now primarily a used-vehicle model, its current market value is particularly relevant when comparing repair costs with potential total-loss thresholds. Battery damage does not automatically establish a total loss. Actual cash value generally reflects model year, mileage, condition, equipment, and comparable used-vehicle transactions rather than original MSRP. If the vehicle is financed, GAP coverage may help address an eligible difference between the insurance settlement and outstanding loan balance, subject to the applicable terms and exclusions.
Questions to ask an insurer
Does your repair network include facilities qualified to service the MINI Cooper SE high-voltage battery and electrical systems?
Does my policy cover battery damage caused by an eligible collision or comprehensive event?
Are required camera, parking-sensor, and driver-assistance recalibrations covered after an eligible repair?
How will you determine the actual cash value of my specific Cooper SE model year and condition?
Does my policy provide coverage for damage to factory-installed charging equipment and electronic components?
What rental reimbursement coverage is available if specialized EV repairs take longer than expected?
How do the available collision and comprehensive deductibles compare with the vehicle's current market value?
Ways to shop smarter
Compare personalized quotes from multiple insurers using the exact MINI Cooper SE model year.
Confirm that the vehicle is the fully electric Cooper SE Hardtop, not the gasoline Cooper S or electric Countryman SE ALL4.
Ask whether the insurer's repair network includes qualified MINI electric vehicle repair facilities.
Review coverage for the high-voltage battery, charging-port assembly, electronics, and related components.
Consider rental reimbursement and roadside assistance coverage.
Compare deductibles against the current market value of the used vehicle.
Review the vehicle's mileage, condition, and battery warranty status when evaluating ownership costs.
Verify charging specifications and EPA range using official documentation for the specific model year.
Frequently asked questions
Which MINI Cooper SE model years were sold in the United States?
The fully electric MINI Cooper SE two-door Hardtop entered the U.S. market for the 2020 model year and was offered through the 2024 model year. The newer-generation electric Cooper introduced overseas was not part of MINI's regular U.S. Cooper lineup for the 2025 through 2027 model years. The electric Countryman SE ALL4 is a separate vehicle.
What is the EPA-estimated range of the MINI Cooper SE?
EPA-estimated range varies by model year. MINI's 2020 U.S. launch documentation listed approximately 110 miles, while later models, including the 2024 Cooper SE, were rated at approximately 114 miles. Actual range depends on driving speed, temperature, terrain, climate-control use, and battery condition.
What battery does the MINI Cooper SE use?
The U.S. Cooper SE uses a lithium-ion high-voltage battery with 32.6 kWh gross capacity and approximately 28.9 kWh usable capacity in MINI's original technical specifications. The battery is positioned low in the vehicle floor in a T-shaped configuration.
What is the MINI Cooper SE battery warranty?
MINI's 2024 U.S. warranty booklet provides high-voltage traction battery coverage against qualifying defects for 8 years or 100,000 miles, whichever occurs first, subject to the applicable warranty conditions. Owners should consult the warranty booklet for their particular model year and confirm remaining coverage.
Does the MINI Cooper SE use CCS or NACS charging?
The U.S.-market 2020-2024 MINI Cooper SE uses CCS1 for DC fast charging and J1772-compatible AC charging. It does not have a factory-installed native NACS charging port. Adapter compatibility should be verified with the manufacturer and charging provider.
Does automobile insurance cover MINI Cooper SE battery replacement?
Physical battery damage resulting from a covered collision or comprehensive event may be covered under the relevant automobile insurance provisions. Normal battery aging and degradation are generally not covered. Qualifying defects may instead be addressed under the manufacturer's battery warranty.
Is the MINI Cooper SE expensive to insure?
Insurance costs depend on the driver, location, model year, vehicle value, insurer, and selected coverage. The Cooper SE's compact size and used-vehicle market value may influence premiums, but specialized EV components and repair costs also matter. Comparing personalized quotes is the most reliable approach.
What happens if my MINI Cooper SE is declared a total loss?
The insurer generally calculates a settlement based on the vehicle's actual cash value, subject to policy terms and applicable state law. This amount may differ significantly from the original purchase price. GAP coverage may help address an eligible difference between the settlement and remaining loan balance, subject to its terms.
How does the electric MINI Cooper SE differ from the gasoline MINI Cooper S for insurance purposes?
The electric Cooper SE uses a high-voltage battery and electric motor rather than a gasoline engine and conventional combustion drivetrain. It also has EV-specific charging equipment and electrical components. These differences may affect repair procedures, parts costs, and insurance pricing. Owners should compare quotes for the exact vehicle rather than assuming the electric and gasoline versions have identical premiums.
Related EV insurance topics
Ready to compare?
Compare EV insurance options and find coverage that fits your needs.