EV Insurance Guide
Fiat 500e
Fiat 500e insurance considerations for the original 2013-2019 and redesigned 2024-2026 electric city cars, including battery differences, J1772 and CCS1 charging, used-vehicle value, limited-production components, safety technology, specialized repairs, and total-loss protection.
Overview
The Fiat 500e is a fully electric, four-passenger city car sold in the United States in two distinct generations: the original 2013-2019 version and the redesigned model introduced for 2024. Both are compact, front-wheel-drive electric hatchbacks, but their battery systems, charging equipment, electronic features, and replacement parts differ substantially.
The first-generation 500e was produced primarily for selected U.S. markets, initially California, before Fiat ended North American production in 2019. It used a 24 kWh lithium-ion battery and a front electric motor rated at 111 horsepower. EPA-estimated range was 87 miles for earlier years and 84 miles for later versions. These were new-vehicle ratings, not guarantees of range in an aging battery.
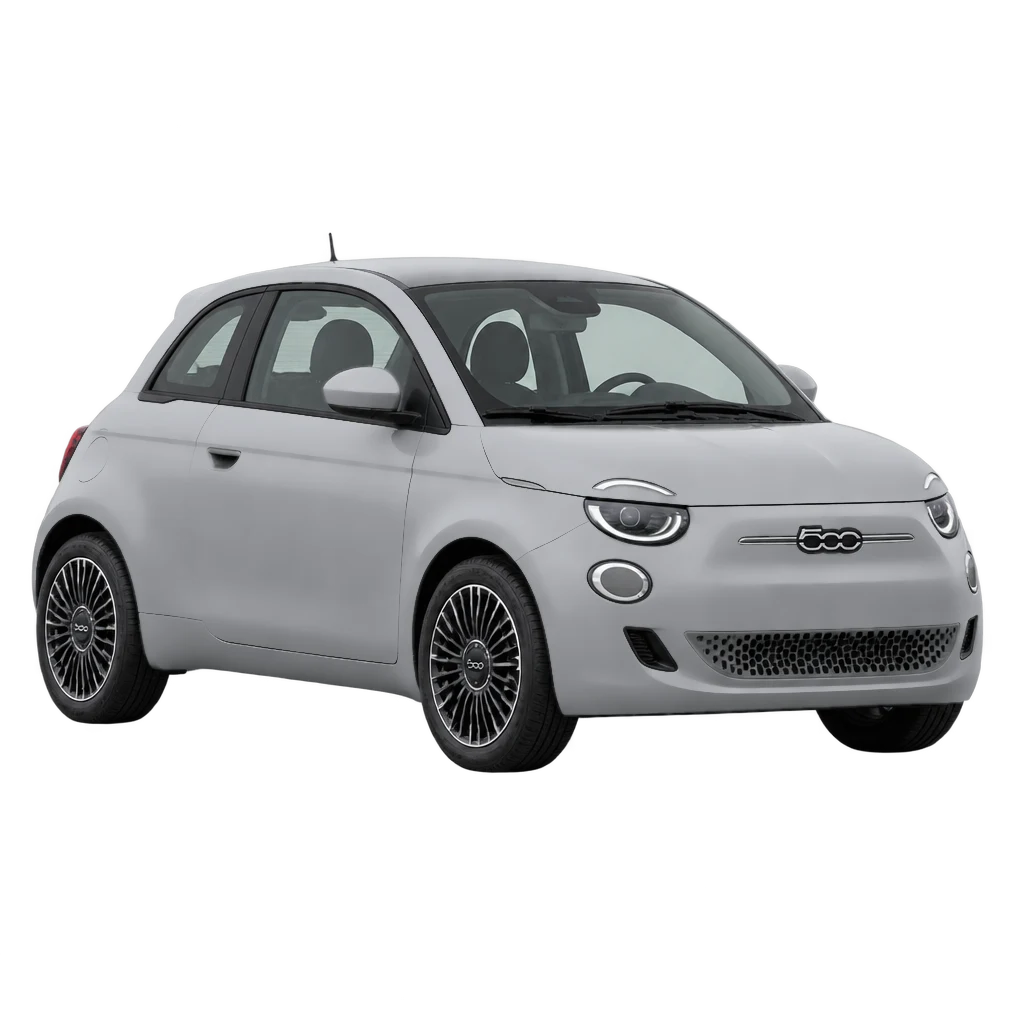
The original 500e supports J1772 Level 1 and Level 2 AC charging, with a 6.6 kW onboard charger. It did not have factory DC fast-charging capability. This distinction matters when shopping for a used vehicle and identifying damaged charging components.
Fiat returned to the U.S. electric vehicle market for 2024 with a substantially redesigned 500e built in Italy. The newer model uses a 42 kWh lithium-ion battery, an approximately 117-horsepower electric motor, and CCS1 DC fast charging rated up to 85 kW. EPA-estimated range varies by year and equipment, with up to 149 miles on certain configurations.
The newer 500e features a modern digital cockpit, updated electronic safety equipment, regenerative braking modes, and available driver-assistance technology. Special editions and 2026 Pop and Icona configurations have different equipment, trim materials, wheels, and vehicle values.
The Fiat 500e is distinct from the gasoline-powered Fiat 500, the larger Fiat 500X, and the newer Fiat Topolino. These vehicles should not be treated as interchangeable for insurance, repairs, or valuations.
Insurance considerations include battery age on older examples, generation-specific charging ports, availability of qualified Fiat EV repair facilities, compact body construction, factory electronics, and current market value.
Owners should identify the VIN, model year, generation, battery and charging equipment, trim, condition, annual mileage, coverage limits, and deductibles when requesting insurance quotes.
How Much Does Fiat 500e Insurance Cost?
Fiat 500e insurance premiums depend on the individual driver, vehicle generation, garaging location, driving history, coverage choices, and insurer underwriting. There is no single nationwide premium that accurately represents every 500e owner. The original 2013-2019 Fiat 500e and the redesigned 2024-2026 version have very different values, charging systems, electrical architectures, and repair requirements. Personalized quotes should identify the actual model year and VIN. Driving record, claims history, annual mileage, vehicle use, garaging location, liability limits, deductibles, and other legally permitted factors may affect insurance costs. For older first-generation vehicles, current used-market value is particularly important. Collision and comprehensive protection should be evaluated against the vehicle's actual cash value, selected deductibles, and premiums. The first-generation 500e's relatively small battery and limited original market availability can make replacement-part sourcing and specialized repairs important after certain covered accidents. Some high-voltage components and original-generation parts may be difficult to obtain. However, limited parts availability does not automatically mean every repair is expensive or that every damaged vehicle is a total loss. The redesigned 500e introduces a larger 42 kWh battery, factory DC fast charging, newer electronic equipment, and different body components. Its repair estimates and vehicle valuation may therefore differ from those of the original model. Trim and factory equipment also matter. Newer Pop, Icona, special-edition, and other configurations may have different wheels, interior finishes, lighting, sensors, and vehicle values. Certain covered accidents may require qualified inspection of battery protection structures, high-voltage equipment, electrical connections, and charging components. A required battery inspection does not automatically mean the battery must be replaced. The 500e's compact body, glass, lighting, and electronic safety systems may affect specific covered repair estimates. Newer vehicles with additional driver-assistance features may require camera or sensor calibration after certain repairs. Charging equipment should be identified accurately. The original model has AC charging only, while the redesigned version supports CCS1 DC fast charging. Owners should compare liability, collision, comprehensive, uninsured or underinsured motorist protection, applicable medical benefits, towing, rental reimbursement, and optional loan or lease gap coverage. Manufacturer battery warranties and recall remedies are separate from standard automobile insurance. Ordinary battery degradation, gradual capacity loss, and unrelated electrical failure generally are not insured physical damage. SureEV does not invent national premium averages, guarantee specific discounts, or promise that every insurer will offer the same Fiat 500e coverage.
What affects insurance cost
Several factors specific to the Fiat 500e are worth understanding when shopping for insurance.
Model Year, Generation, and Market Value
The original 2013-2019 Fiat 500e and redesigned 2024-2026 model differ substantially in battery equipment, body components, technology, and vehicle value. Mileage, condition, trim, and current market value may influence insurance classification and total-loss valuation.
Battery Age and High-Voltage Equipment
The first-generation 500e uses a 24 kWh battery, while the redesigned model uses a 42 kWh battery. Certain covered collisions may require qualified high-voltage inspection. Ordinary battery degradation, age-related capacity loss, and unrelated electrical failure generally are not insured physical damage.
Charging Systems and Generation Differences
The original 500e uses J1772 AC charging without factory DC fast charging. The 2024-2026 model adds CCS1 DC charging rated up to 85 kW. Charging-port repairs and replacement components must match the actual generation.
Replacement Parts and Qualified Repair Facilities
Some first-generation electric-specific components may be difficult to source because of the vehicle's age and limited original distribution. Newer 500e models use different body panels, electrical equipment, and repair procedures. Parts availability and qualified labor vary.
Compact Body, Glass, and Safety Technology
The Fiat 500e's compact hatchback construction, lighting, glass, electronic controls, and available driver-assistance systems may influence certain covered repairs. Newer configurations can require camera or sensor inspection or calibration that should not be assumed necessary on older models.
Driver Profile, Coverage, and Deductibles
Driving history, claims experience, garaging location, annual mileage, vehicle use, coverage limits, deductibles, and insurer underwriting affect personalized premiums. Owners of older 500e vehicles should also evaluate physical damage coverage against current market value.
Battery and insurance
The Fiat 500e uses a lithium-ion traction battery that supplies electrical energy to its front-mounted electric drive motor. Battery construction differs substantially between generations. The original 2013-2019 U.S. model has a 24 kWh liquid-cooled and heated high-voltage battery. The redesigned 2024-2026 U.S. version uses a larger 42 kWh lithium-ion pack and a different electrical architecture. These battery packs, associated components, and repair procedures should not be assumed interchangeable. Collision coverage may apply to eligible physical battery damage caused by an insured accident. Comprehensive coverage may address qualifying non-collision events, including certain fires, flooding, and falling objects. Actual coverage depends on the cause of loss, policy wording, exclusions, deductibles, and applicable state requirements. Ordinary battery degradation, gradual capacity loss, wear, and unrelated electrical or mechanical breakdowns generally fall outside standard automobile insurance. For older 500e vehicles, battery condition deserves particular attention. The original EPA range rating does not establish the remaining range or battery health of a vehicle that has been in service for many years. Owners should not assume that the original manufacturer battery warranty remains active. Coverage depends on the applicable warranty's time, mileage, and other conditions. Newer 500e models have separate manufacturer warranty terms and battery components. Those warranties are not substitutes for collision or comprehensive insurance. Significant collisions, underbody impacts, or flooding may require qualified inspection of battery protective structures, cooling equipment, electrical isolation systems, mounting points, and high-voltage connections. Repair facilities should follow the procedures applicable to the exact vehicle generation. A necessary inspection does not automatically mean complete battery replacement. Replacement-part availability may affect older cars because their battery technology and original distribution differ from newer 500e models. Charging equipment also requires accurate identification. The original model has J1772 AC charging, while the redesigned 500e adds CCS1 DC fast charging and associated high-voltage electronics. Physical damage to installed charging components caused by an eligible insured event may qualify for coverage, subject to policy terms. Portable charging cables, adapters, and home charging equipment may require different coverage arrangements. Owners should never attempt to open, disconnect, charge, or repair suspected damaged high-voltage equipment. When reviewing insurance, ask about eligible battery damage, approved repair procedures, specialized labor, electrical diagnostics, towing, and replacement-part availability.
Repair considerations
Repairing a Fiat 500e requires identifying whether the vehicle belongs to the original 2013-2019 generation or the redesigned 2024-2026 generation. Although both vehicles share the 500e name and compact styling, their battery systems, charging hardware, electric drivetrains, body construction, and electronic components differ. Parts from the gasoline-powered Fiat 500 or another 500e generation should not automatically be considered interchangeable. Qualified repair facilities may need Fiat or Stellantis service information, electrical safety equipment, specialized diagnostic tools, and model-specific replacement components. After certain covered collisions or underbody impacts, technicians may need to inspect battery protection structures, cooling lines, high-voltage connections, drive-motor equipment, and surrounding components. Not every exterior accident requires work on the high-voltage system. Inspections should reflect actual damage and the applicable manufacturer procedures. The 500e's compact body includes model-specific bumpers, doors, lighting, exterior glass, rear hatch components, and structural elements. The redesigned 500e has different body panels, safety systems, and factory electronics from the original U.S. version. Repair estimates must reflect the correct generation. Certain newer configurations include distinctive wheels, exterior trim, interior components, premium materials, and special-edition equipment. Limited original distribution and vehicle age may complicate sourcing certain first-generation electrical and body components. Availability depends on actual parts and suppliers rather than age alone. The original 500e's charging system uses J1772 AC equipment and a 6.6 kW onboard charger. The new-generation model supports CCS1 DC fast charging and has different charging electronics. Technicians should not assume that a first-generation 500e can be repaired using second-generation charging components. The redesigned vehicle also incorporates modern electronic systems, including updated digital displays, regenerative braking controls, and available driver-assistance technology. Certain windshield, bumper, mirror, or electronic repairs may require camera and sensor inspection or manufacturer-specified calibration on appropriately equipped newer vehicles. Owners should ask whether their insurer's repair network can service their particular Fiat 500e generation, obtain compatible parts, and perform required electrical safety procedures. For older vehicles, specialized repair expenses may approach a modest current market value and influence an insurer's total-loss determination. Towing and rental reimbursement may help with eligible transportation expenses during covered repairs, subject to policy limits and exclusions.
Cameras, sensors, glass and technology
The Fiat 500e's electronic systems differ significantly between the original 2013-2019 model and the redesigned 2024-2026 vehicle. Original 500e models have safety and electronic features typical of their production period, including electronic stability control, traction control, antilock braking, occupant protection systems, and basic infotainment equipment. These earlier vehicles do not have the same modern driver-assistance hardware and calibration requirements as certain newer 500e configurations. However, original-generation models still include battery-management electronics, charging controls, regenerative braking, electric propulsion modules, and other systems that may require specialized diagnosis after certain covered losses. The redesigned 500e adds a modern digital driver display, an available 10.25-inch Uconnect 5 touchscreen, updated infotainment software, and additional electronic safety equipment. Depending on trim and factory options, newer vehicles may include automatic emergency braking, lane-keeping support, blind-spot monitoring, adaptive cruise control, and other driver-assistance features. Some specially equipped 500e models include hands-on Level 2 driver assistance. This is not autonomous driving, and it should not be confused with GM's Super Cruise technology. Not every 500e includes the same electronic features. Equipment should be verified using the actual model year, trim, and VIN. After certain covered windshield, front bumper, mirror, or collision repairs, installed cameras and sensors may require diagnosis or manufacturer-specified calibration. A first-generation vehicle without those systems should not automatically be assigned the same procedures. The newer 500e's digital displays, lighting, parking features, infotainment equipment, and electronic controls may require specialized replacement parts if physically damaged. The vehicle's small dimensions do not automatically mean its glass or electronic repairs are inexpensive. Physical damage to factory-installed electronics caused by an eligible insured event may qualify under applicable collision or comprehensive provisions. Ordinary software maintenance, subscriptions, wear, and unrelated electrical malfunction generally are not covered physical damage. An electronic warning does not automatically establish that a camera, sensor, or control module needs replacement. Qualified diagnosis and applicable manufacturer procedures should determine the appropriate repair. Owners should ask insurers how eligible electronic repairs, camera calibration, replacement components, and specialized labor are handled.
Coverage considerations
Fiat 500e owners should compare liability, collision, comprehensive, uninsured or underinsured motorist protection, and applicable medical coverage. Requirements and benefits vary by state and insurer. Liability insurance generally addresses qualifying injuries or property damage for which the insured driver is legally responsible. It generally does not pay to repair the owner's own Fiat 500e. Collision coverage may apply to eligible accident-related damage involving the high-voltage battery, front electric drive motor, body structure, charging equipment, glass, or factory-installed electronics. Comprehensive coverage generally addresses qualifying non-collision losses, including theft, certain fires, flooding, hail, and falling objects. Coverage depends on policy terms, exclusions, deductibles, and the cause of loss. The 2013-2019 and 2024-2026 Fiat 500e generations have different battery systems, body construction, charging equipment, and electronic features. Insurers and repair facilities should identify the actual vehicle rather than assume identical components. For older first-generation vehicles, current actual cash value is particularly important when deciding whether collision and comprehensive coverage remain financially worthwhile. Limited original U.S. distribution and the age of some first-generation 500e vehicles may affect replacement-part availability. Owners should confirm access to qualified repairs following an eligible covered loss. The redesigned Fiat 500e uses a larger battery, factory CCS1 fast charging, different body components, and updated electronics. Repair estimates and coverage discussions should account for these differences. Certain covered collisions or underbody impacts may require specialized battery inspections, electrical diagnostics, or manufacturer-specified safety procedures. A required inspection does not automatically mean the entire battery must be replaced. Ordinary battery degradation, gradual capacity loss, wear, and unrelated mechanical or electrical failure generally fall outside standard auto insurance. Manufacturer warranties and recalls operate separately. The original Fiat 500e lacks factory DC fast charging, while the redesigned model includes CCS1 charging hardware. Eligible charging-system damage should be evaluated according to the actual vehicle. Newer models with cameras, sensors, and driver-assistance systems may require calibration after certain covered windshield or collision repairs. Owners should also review towing, roadside assistance, rental reimbursement, and optional loan or lease gap protection where applicable. Compare personalized quotes with equivalent liability limits, physical damage deductibles, and optional benefits.
Deductibles
A deductible is the amount an insured owner is responsible for paying toward an eligible covered claim before the applicable insurer payment. Collision and comprehensive insurance commonly have separate deductibles. Higher deductibles may reduce premiums but increase out-of-pocket expenses after an eligible covered loss. Lower deductibles generally have the opposite effect. The Fiat 500e's generation and current market value are particularly important when selecting deductibles. For an older 2013-2019 Fiat 500e, a deductible representing a substantial portion of the vehicle's value may limit the usefulness of certain physical damage claims. Owners should compare collision and comprehensive premiums, deductible amounts, and potential claim payments based on the vehicle's present value rather than its original purchase price. The redesigned 2024-2026 Fiat 500e may have a different value and repair exposure because of its newer battery, CCS1 fast-charging equipment, electronic systems, and body components. Certain covered repairs may require qualified high-voltage technicians, replacement parts, electronic diagnostics, or camera calibration. However, not every accident involves these systems. Glass coverage and applicable deductibles deserve attention because certain newer 500e configurations may require camera or sensor inspection following windshield repairs. Older vehicles generally have different electronic equipment and should not automatically be assigned the same calibration procedures. Owners financing or leasing a Fiat 500e should review any coverage requirements or deductible limitations in their agreements. Choose deductibles that remain financially manageable, and compare personalized quotes using consistent coverage limits and deductible amounts. Review collision and comprehensive protection periodically as the vehicle ages, mileage increases, and market value changes.
Accidents and total loss
Following an accident involving a Fiat 500e, personal safety comes first. Request emergency assistance when appropriate and avoid contact with suspected damaged high-voltage equipment. Significant collisions, underbody impacts, or flooding may require qualified inspection before the vehicle is operated or charged. Repair estimates should identify the correct Fiat 500e generation, model year, battery configuration, charging equipment, trim, and actual damaged components. The original 2013-2019 500e has a smaller battery, different charging hardware, and different body components from the redesigned 2024-2026 model. Certain repairs may involve the battery enclosure, front electric drive motor, cooling equipment, charging electronics, high-voltage wiring, body panels, glass, or electronic controls. A required battery inspection does not automatically establish that complete battery replacement is necessary or that the vehicle is a total loss. For older first-generation vehicles, current market value and availability of compatible replacement components can significantly influence whether a damaged 500e is economically repairable. An insurer may declare a Fiat 500e a total loss when applicable policy and state-law criteria are satisfied. Repair costs, vehicle value, salvage considerations, and jurisdiction-specific requirements may be relevant. Under standard actual cash value coverage, an eligible total-loss settlement generally reflects the vehicle's value immediately before the loss, subject to policy terms and applicable law. Original purchase price does not automatically determine current insured value. Valuation should consider the correct generation, model year, mileage, condition, factory options, relevant battery service history, and suitable comparable Fiat 500e vehicles. A gasoline-powered Fiat 500 should not automatically be used as an identical comparable vehicle because its propulsion equipment and market characteristics differ. Likewise, a first-generation 500e should not automatically be valued as equivalent to the redesigned 2024-2026 version. Owners should review valuation reports for incorrect generation identification, missing factory equipment, mileage errors, inaccurate condition descriptions, or unsuitable comparable vehicles. Window stickers, service records, photographs, documented battery work, and relevant market listings may help support accurate valuation. For financed or leased vehicles, optional loan or lease gap protection may address certain qualifying differences between an eligible settlement and an outstanding balance, subject to contract conditions. Owners disputing a valuation should follow applicable policy procedures and state requirements.
Questions to ask an insurer
Does your quote correctly identify my Fiat 500e VIN, model year, original 2013-2019 or redesigned 2024-2026 generation, trim, mileage, condition, and current market value?
Does collision or comprehensive insurance cover eligible physical damage to the 500e's traction battery, electric motor, charging equipment, and associated high-voltage systems, and what exclusions apply?
Can I use a repair facility qualified to service my specific Fiat 500e generation, and how does the insurer handle necessary battery inspections, specialized labor, and replacement-part availability?
For an older 500e, how does the insurer handle claims when compatible high-voltage battery components, electric drivetrain parts, or generation-specific replacement equipment are difficult to obtain?
How does the insurer handle eligible charging-system damage, including J1772 AC equipment on the original 500e or CCS1 DC fast-charging components on the redesigned model?
If my Fiat 500e is declared a total loss, will the valuation account for the correct generation, model year, mileage, condition, factory equipment, and appropriate comparable electric 500e vehicles?
What liability limits, collision and comprehensive deductibles, uninsured or underinsured motorist coverage, towing, rental reimbursement, and optional loan or lease gap benefits are available?
Ways to shop smarter
Request personalized insurance quotes using the correct Fiat 500e VIN, model year, generation, trim, mileage, condition, garaging location, and driver information.
Compare equivalent liability limits, collision and comprehensive deductibles, uninsured or underinsured motorist protection, and optional benefits.
For an original 2013-2019 Fiat 500e, evaluate whether physical damage coverage remains financially worthwhile based on current market value, premiums, deductibles, and repair considerations.
Ask how eligible physical damage to the high-voltage battery, electric drive motor, charging hardware, and related electrical equipment is covered.
Verify that the insurer's repair network can service the actual Fiat 500e generation and obtain compatible parts, particularly for older first-generation vehicles.
Identify whether the vehicle uses original-generation J1772 AC charging or redesigned-generation CCS1 DC fast charging, and confirm that relevant equipment is identified correctly.
Review glass coverage, electronic safety-system calibration, towing, roadside assistance, rental reimbursement, and optional gap protection where applicable.
Reevaluate current market value, battery condition, factory equipment, deductibles, coverage needs, annual mileage, and competing quotes at renewal.
Frequently asked questions
Is the Fiat 500e expensive to insure?
Fiat 500e insurance premiums depend on driving history, location, model year, generation, vehicle value, coverage selections, deductibles, and insurer underwriting. The original and redesigned 500e models have different equipment and repair considerations. Personalized quotes are more reliable than unsupported nationwide averages.
Does insurance cover the Fiat 500e battery?
Collision or comprehensive coverage may apply to physical battery damage caused by an eligible insured event, subject to policy terms and deductibles. Ordinary degradation, gradual capacity loss, wear, and unrelated electrical or mechanical failure generally are not covered by standard automobile insurance. Manufacturer warranties operate separately.
What years was the Fiat 500e sold in the United States?
The original Fiat 500e was sold in the United States from the 2013 through 2019 model years. A substantially redesigned 500e returned for 2024 and continued through the 2025 and 2026 model years. The two generations have different batteries, charging systems, and repair components.
Is the Fiat 500e front-wheel drive?
Yes. Both U.S. generations of the Fiat 500e use a front electric motor driving the front wheels. Motor output, battery equipment, body construction, and electronic technology differ between generations.
What is the driving range of the Fiat 500e?
The original Fiat 500e had an EPA-estimated range of approximately 84-87 miles when new, depending on model year. The redesigned 2024-2026 model offers up to approximately 149 miles on certain configurations. Actual range depends on battery condition, driving habits, temperature, terrain, and vehicle equipment.
Does the Fiat 500e support DC fast charging?
The original 2013-2019 Fiat 500e does not have factory DC fast charging and uses J1772 AC charging. The redesigned 2024-2026 model supports CCS1 DC fast charging rated up to approximately 85 kW under suitable conditions. Owners should verify the actual vehicle generation.
Are Fiat 500e replacement parts difficult to find?
Availability varies by model year, generation, component, and supplier. Some parts for older first-generation vehicles may be difficult to obtain because of age and limited original U.S. distribution. Redesigned models use different components and repair procedures. Qualified repair providers can assess current availability.
How is a Fiat 500e valued after a total loss?
Standard actual cash value coverage generally reflects the vehicle's value immediately before an eligible covered loss, subject to policy terms and applicable law. Generation, model year, mileage, condition, factory equipment, and suitable electric 500e comparables may be relevant.
Can I compare Fiat 500e insurance quotes online?
Yes. Insurance comparison services may help Fiat 500e owners explore available quotes, depending on insurer participation, state availability, vehicle eligibility, and underwriting. Compare equivalent coverage limits, deductibles, and optional benefits.
Related EV insurance topics
Ready to compare?
Compare EV insurance options and find coverage that fits your needs.