Tesla Model Y Insurance in New Jersey
New Jersey's 2026 liability requirements, no-fault PIP, Tesla Model Y repair considerations, battery coverage, and how to compare insurance policies.
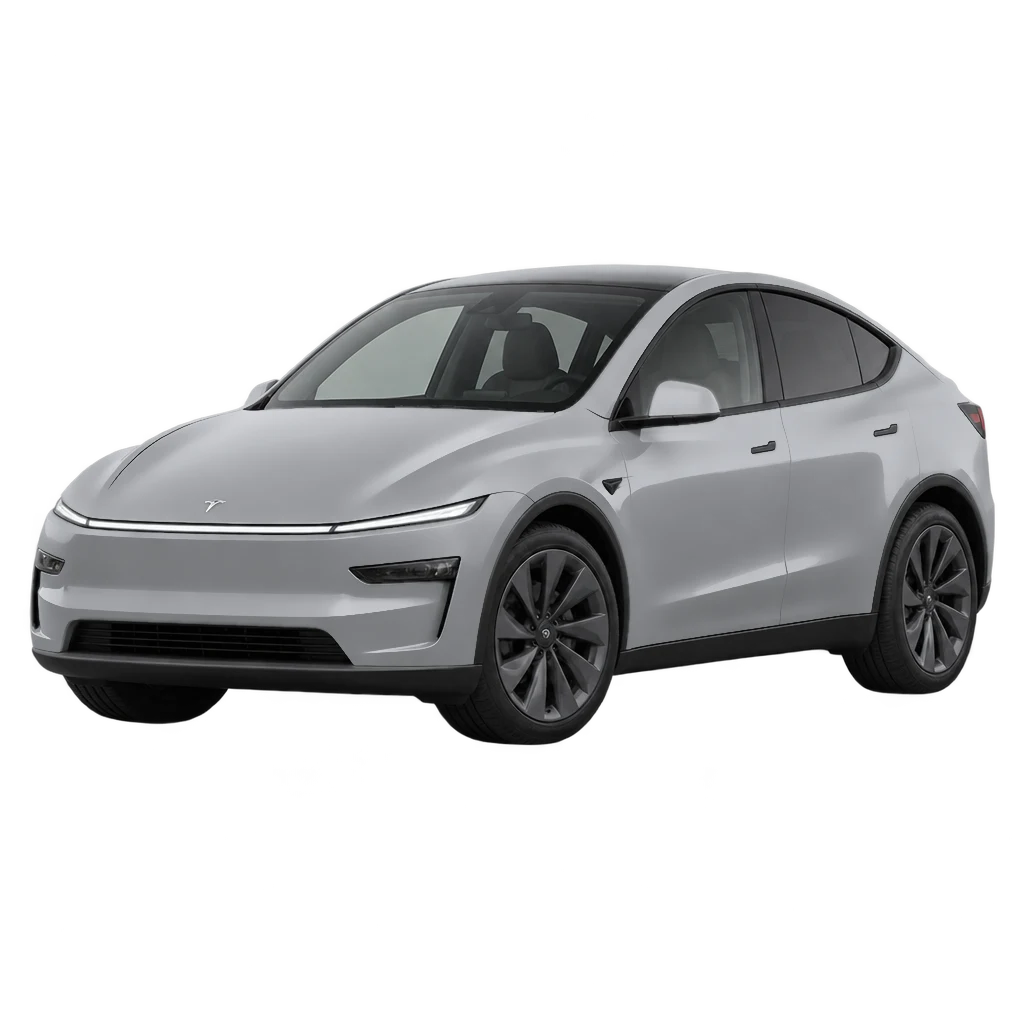
Insuring a Tesla Model Y in New Jersey involves understanding the state's automobile insurance choices as well as the coverage needs of an electric vehicle.
New Jersey offers Standard and Basic auto insurance policies, and the differences can be significant. Drivers should evaluate liability protection, personal injury protection, repair provisions, and physical damage coverage rather than choosing a policy based on price alone.
Whether you drive in Jersey City, Newark, Hoboken, Fort Lee, Princeton, Atlantic City, or elsewhere in New Jersey, your coverage choices should reflect your circumstances and vehicle.
New Jersey Insurance Requirements for the Tesla Model Y
New Jersey requires owners of registered passenger vehicles to maintain qualifying automobile insurance.
For Standard Policies issued or renewed on or after January 1, 2026, the minimum liability limits are:
- $35,000 for bodily injury or death to one person.
- $70,000 for bodily injury or death to multiple people in one accident.
- $25,000 for property damage in one accident.
These minimums are commonly expressed as 35/70/25.
The bodily injury minimums increased in 2026. Drivers should not rely on older references listing 25/50/25 as the current Standard Policy minimum.
Standard Policies also include required personal injury protection and uninsured/underinsured motorist coverage, subject to applicable coverage requirements.
New Jersey also offers a separate Basic Policy with lower minimum benefits and important coverage limitations.
Standard Policy vs. Basic Policy in New Jersey
The Standard Policy offers a broader range of liability limits, personal injury protection choices, and optional coverages.
The Basic Policy provides a more limited alternative that can satisfy New Jersey's minimum insurance requirements for eligible passenger vehicles.
Under the Basic Policy:
- Property damage liability is $5,000 per accident.
- Bodily injury liability is not automatically included, although $10,000 per accident may be available as an option.
- Basic personal injury protection provides $15,000 per person per accident, with special additional benefits for certain serious injuries.
- Uninsured and underinsured motorist coverage is not included.
- Collision and comprehensive coverage may be available from some insurers.
A Basic Policy may leave a driver exposed to substantial financial risk following a serious accident.
Tesla Model Y owners should carefully evaluate whether the Basic Policy's limited protection is appropriate for their circumstances.
How New Jersey Personal Injury Protection Works
New Jersey is a no-fault insurance state.
Personal Injury Protection, commonly called PIP, can help pay eligible medical expenses following an automobile accident regardless of who caused it, subject to policy terms and applicable law.
The minimum standard PIP medical expense limit is generally $15,000, with higher options available under Standard Policies.
Certain qualifying serious injuries may be eligible for additional medical benefits up to $250,000 under applicable statutory provisions.
PIP coverage choices can affect deductibles, available medical benefits, and the relationship between automobile insurance and health insurance.
Drivers should review their PIP selection carefully rather than assuming every New Jersey policy provides the same benefits.
New Jersey's Right-to-Sue Options
New Jersey Standard Policy customers generally choose between the Limitation on Lawsuit option and the No Limitation on Lawsuit option.
The Limitation on Lawsuit option restricts the circumstances in which an injured person may pursue compensation for pain and suffering after an automobile accident.
The No Limitation on Lawsuit option provides broader rights to pursue qualifying non-economic damages, subject to applicable law.
These choices can affect premiums and legal rights.
Drivers should understand the differences before selecting an option. This guide does not provide legal advice.
What Affects Tesla Model Y Insurance Costs in New Jersey?
There is no universal insurance premium for New Jersey Model Y owners.
Pricing can depend on:
- Driving record and experience.
- Garaging address and vehicle usage.
- Annual mileage.
- Model Y model year and configuration.
- Selected liability limits and PIP options.
- Collision and comprehensive deductibles.
- Insurer rating rules and available discounts.
- Vehicle repair costs and claims experience.
Insurance considerations in densely populated areas such as Jersey City or Newark may differ from those in less densely populated communities.
However, location alone does not establish an individual's premium.
Compare quotes using equivalent vehicle details, liability limits, PIP selections, lawsuit options, and deductibles.
Coverage Worth Considering for a New Jersey Model Y
Collision Coverage
Collision coverage can help pay for eligible damage to your Model Y after a collision with another vehicle or object, subject to your deductible and policy conditions.
Tesla repairs may require specialized body components, diagnostics, and manufacturer procedures.
Comprehensive Coverage
Comprehensive insurance generally covers eligible non-collision losses, including theft, vandalism, fire, flooding, falling objects, and certain storm damage.
New Jersey drivers should consider coastal flooding, severe weather, and other risks relevant to where the vehicle is parked.
Uninsured and Underinsured Motorist Coverage
New Jersey Standard Policies include uninsured and underinsured motorist protection under applicable requirements.
These coverages can help when another driver is uninsured or lacks sufficient coverage, subject to policy limits and conditions.
The Basic Policy does not include this protection.
Rental Reimbursement and Roadside Assistance
Specialized repairs and replacement-part availability may affect how long a Model Y remains at a repair facility.
Rental reimbursement can help with eligible transportation costs during covered repairs. Review daily limits, maximum periods, and EV-specific roadside assistance provisions.
Tesla Model Y Battery Insurance and Warranty
The Model Y's high-voltage battery is an important vehicle component, but standard automobile insurance and manufacturer warranty coverage serve different purposes.
Battery damage resulting from a covered collision, fire, or another insured event may qualify for collision or comprehensive benefits.
Ordinary battery degradation, manufacturing defects, and mechanical failures generally are not covered by standard automobile insurance.
Tesla provides separate battery and drive unit warranty protection. Terms and mileage limits vary by model year, configuration, and applicable warranty documentation.
Review the warranty that applies to your specific vehicle.
Tesla Repairs, Glass, and Technology
The Model Y includes cameras, glass components, electronic controls, and integrated driver-assistance systems.
Certain repairs may require manufacturer procedures, specialized diagnostics, or post-repair checks.
Tesla operates collision centers and maintains an approved repair network.
Before selecting an insurer, ask:
- Can I use a Tesla-approved collision repair facility?
- How are original Tesla replacement parts handled?
- Are necessary diagnostics and repair procedures covered?
- What deductible applies to windshield or glass damage?
- How long will rental reimbursement remain available?
Claims procedures and covered expenses vary by insurer and policy.
New Jersey Flooding, Winter Weather, and Road Risks
New Jersey drivers can face coastal flooding, heavy rain, snow, ice, and falling debris.
Comprehensive coverage may apply to eligible flood damage, falling objects, and certain non-collision storm losses.
Collision coverage may apply to covered accidents involving slippery roads or other driving-related events.
Liability insurance and PIP do not replace physical damage protection for your own Model Y.
Review comprehensive and collision deductibles before a loss occurs.
How to Compare Tesla Model Y Insurance in New Jersey
When comparing policies, review:
- Standard versus Basic Policy protection.
- Liability limits, including the 2026 Standard Policy minimums.
- PIP benefits and deductibles.
- Right-to-sue options.
- Uninsured and underinsured motorist protection.
- Collision and comprehensive coverage.
- Tesla repair provisions and glass coverage.
- Rental reimbursement and roadside assistance.
If your Model Y is financed or leased, the lender or leasing company may require collision and comprehensive insurance.
GAP protection may also be worth considering when your loan or lease balance could exceed the vehicle's insured value following a total loss. Compare equivalent coverage selections rather than choosing solely by the lowest quoted premium.
Frequently Asked Questions
What is the minimum Tesla Model Y insurance required in New Jersey?
For Standard Policies issued or renewed beginning January 1, 2026, New Jersey's minimum liability limits are 35/70/25. A separate Basic Policy exists with different, more limited coverage requirements.
Does New Jersey require PIP for a Tesla Model Y?
Yes. New Jersey generally requires PIP for qualifying passenger vehicle policies. The minimum medical expense benefit is generally $15,000, with additional provisions for certain serious injuries.
Does New Jersey require full coverage on a Model Y?
New Jersey generally does not require collision or comprehensive insurance by law for privately owned passenger vehicles. However, lenders and leasing companies may require both. "Full coverage" is not a standardized insurance policy.
Does insurance cover a Tesla Model Y battery?
Battery damage from a covered collision or comprehensive event may qualify for insurance benefits. Ordinary degradation, mechanical breakdown, and manufacturing defects generally are not covered by standard automobile insurance.
Compare Tesla Model Y Insurance Options
New Jersey Model Y owners should compare liability limits, PIP benefits, lawsuit options, physical damage protection, and Tesla-specific repair provisions before choosing an insurer. Understanding these differences can help you evaluate available insurance options.
About This Guide
SureEV provides general educational information and access to insurance comparison services. SureEV is not an insurance carrier and does not issue, underwrite, or bind policies. Coverage availability, eligibility, rates, and terms depend on the insurer and applicant. This guide is not personalized insurance advice.