Tesla Model Y Insurance in Georgia
Georgia liability insurance requirements, uninsured motorist options, Tesla Model Y battery protection, specialized repairs, severe weather, and how to compare policies.
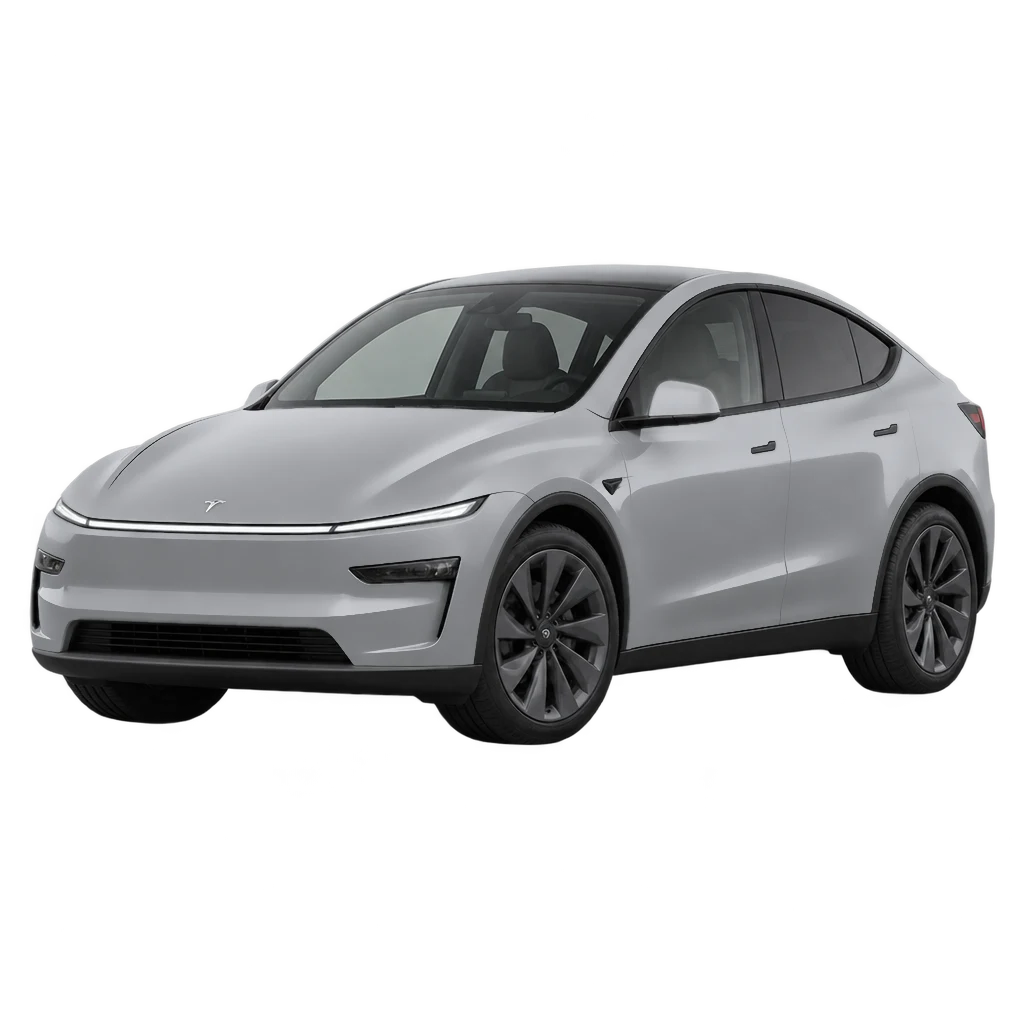
Insuring a Tesla Model Y in Georgia involves understanding the state's automobile liability insurance requirements and evaluating coverage for the vehicle's high-voltage battery, glass, cameras, electronics, and specialized repairs.
Georgia drivers may also encounter severe thunderstorms, hail, tornadoes, flooding, and falling trees, making physical damage protection worth examining.
Whether you drive in Atlanta, Savannah, Augusta, Columbus, Macon, Athens, or elsewhere in Georgia, the right policy depends on your Model Y, driving circumstances, and selected coverage.
Georgia Insurance Requirements for the Tesla Model Y
Georgia requires drivers to maintain qualifying automobile liability insurance to operate vehicles on public roads.
For standard private passenger automobile policies, Georgia's minimum liability limits are 25/50/25:
- $25,000 for bodily injury or death to one person in an accident.
- $50,000 for bodily injury or death to multiple people in one accident.
- $25,000 for property damage in one accident.
Liability insurance helps pay for covered injuries and property damage you cause to others.
It generally does not pay to repair your own Tesla Model Y following an at-fault collision.
Higher liability limits may be worth considering because serious injuries or damage involving multiple vehicles can exceed Georgia's statutory minimums.
Georgia does not generally require drivers to purchase collision or comprehensive insurance, although lenders and leasing companies may require both.
Uninsured and Underinsured Motorist Coverage in Georgia
Georgia automobile liability policies generally include uninsured motorist coverage unless the insured rejects it in writing.
This protection can help with eligible losses caused by uninsured drivers and, under applicable terms, drivers whose liability coverage is insufficient.
Georgia offers two important uninsured motorist coverage approaches.
Add-On Uninsured Motorist Coverage
Add-on coverage can provide eligible protection in addition to the at-fault driver's available liability coverage, subject to the selected uninsured motorist limits and policy terms.
This can be particularly relevant when an at-fault driver has insurance but not enough to cover the loss.
Reduced-By Uninsured Motorist Coverage
Reduced-by coverage generally reduces the available uninsured motorist benefit by the applicable at-fault driver's liability coverage.
The insured can select this alternative through the applicable written election process.
Georgia drivers may also reject uninsured motorist coverage in writing or select permitted lower limits.
Uninsured motorist coverage may include bodily injury and property damage components, subject to policy provisions, deductibles, and eligibility rules.
When comparing policies, confirm whether uninsured motorist coverage is add-on or reduced-by rather than assuming the two provide identical benefits.
What Affects Tesla Model Y Insurance Costs in Georgia?
There is no universal insurance premium for Georgia Model Y owners.
Pricing can depend on:
- Driving record and experience.
- Garaging address and annual mileage.
- Model Y model year and configuration.
- Selected liability and optional coverage limits.
- Collision and comprehensive deductibles.
- Insurer-approved rating factors and available discounts.
- Vehicle repair costs and relevant claims experience.
- Applicable underwriting rules.
Model Y configurations differ by model year, drive system, battery, and equipment.
The correct vehicle identification information matters when requesting quotes.
Insurance considerations in the Atlanta metropolitan area may differ from those in smaller Georgia communities, but location alone does not determine an individual's premium.
Compare quotes using equivalent driver details, vehicle information, limits, and deductibles.
Coverage Worth Considering for a Georgia Model Y
Collision Coverage
Collision insurance can help pay for covered damage to your Model Y after a collision with another vehicle or object, subject to your deductible and policy terms.
Tesla repairs may involve specialized body components, electronics, and manufacturer procedures.
Comprehensive Coverage
Comprehensive insurance generally covers eligible non-collision losses such as theft, vandalism, fire, hail, flooding, and falling objects.
Georgia Model Y owners may want to consider hailstorms, falling trees, severe thunderstorms, and other risks relevant to where the vehicle is parked.
Medical Payments Coverage
Medical payments coverage may help pay certain eligible medical expenses following an automobile accident, regardless of fault.
This coverage is generally optional in Georgia.
Review available limits, eligibility, and coordination with other insurance.
Glass Coverage
The Model Y includes a windshield and other glass components that may require specialized replacement procedures.
Glass claims may be handled under comprehensive coverage, subject to the policy's applicable deductible and conditions.
Do not assume Georgia provides universal zero-deductible windshield replacement.
Ask about available glass-specific options and necessary camera or sensor checks after replacement.
Rental Reimbursement and Roadside Assistance
Rental reimbursement may help pay eligible transportation expenses while your Model Y undergoes repairs following a covered loss.
Roadside assistance may provide towing or other services after an eligible breakdown or incident.
Tesla also provides manufacturer roadside assistance under applicable vehicle and warranty terms, which is separate from insurance roadside coverage.
Review benefit limits, exclusions, repair-delay provisions, and Tesla-recommended towing procedures.
Tesla Model Y Battery Insurance and Warranty
The Model Y's high-voltage battery is a major vehicle component, but automobile insurance and Tesla's manufacturer warranty serve different purposes.
Battery damage caused by a covered collision, fire, flood, or another insured event may qualify for collision or comprehensive benefits.
Ordinary battery degradation, mechanical failure, and manufacturing defects generally are not covered by standard automobile insurance.
Tesla provides a separate Battery and Drive Unit Limited Warranty for qualifying Model Y vehicles.
Depending on model year and configuration, the warranty generally lasts eight years with a mileage limit such as 100,000 or 120,000 miles, whichever comes first.
Tesla's applicable warranty terms also specify a minimum 70% battery capacity retention provision during the warranty period.
Warranty eligibility, mileage limits, exclusions, and covered components depend on the documentation applicable to the exact vehicle.
Do not assume every Model Y has identical warranty coverage.
The manufacturer warranty does not replace automobile insurance for accidental damage.
Tesla Model Y Repairs, Glass, and Driver Assistance
The Tesla Model Y uses cameras, electronic control systems, glass components, and integrated driver-assistance technology.
Depending on model year, equipment, software, and subscriptions, available driver-assistance capabilities can vary.
Autopilot or Full Self-Driving (Supervised) features do not make the vehicle autonomous or eliminate the driver's responsibility to supervise driving.
Some collision and glass repairs may require specialized diagnostics, camera calibration, or manufacturer procedures.
Tesla operates collision centers and maintains a network of approved collision repair facilities.
Before choosing an insurer, ask:
- Can I use a Tesla-approved collision repair facility?
- How does the policy handle original Tesla replacement parts?
- Are required diagnostics and camera calibrations covered?
- What deductible applies to windshield and other glass damage?
- Are high-voltage system inspections covered when required after an accident?
- How long will rental reimbursement remain available if repairs are delayed?
Repair facility choices, covered expenses, and claims procedures vary by insurer and policy.
Charging Equipment and Insurance Considerations
The Tesla Model Y supports AC charging and compatible DC fast charging.
Charging equipment and accessories can vary by model year and configuration.
Automobile insurance does not automatically cover every charging-related expense.
Damage to the vehicle's charging port or related components caused by a covered insured event may qualify for applicable physical damage coverage.
A permanently installed home charging station may instead fall under homeowners or another property insurance policy, depending on ownership, installation, and policy terms.
Portable charging equipment and adapters may receive different coverage treatment.
Ask the relevant insurer how charging equipment and accessories are classified rather than assuming coverage.
Georgia Severe Weather, Flooding, and Storm Damage
Georgia drivers can face thunderstorms, hail, tornadoes, flooding, and falling trees.
Coastal areas may also experience tropical storms or hurricane-related effects.
Comprehensive coverage may respond to eligible hail, flood, windstorm, and falling-object losses.
Collision coverage may apply to covered driving-related accidents.
Georgia's mandatory liability insurance does not provide physical damage protection for your own Tesla Model Y.
Review deductibles, exclusions, and claims procedures before severe weather occurs.
For a flood-damaged electric vehicle, do not attempt to charge or operate it until qualified professionals have evaluated it in accordance with manufacturer and emergency safety guidance.
How to Compare Tesla Model Y Insurance in Georgia
When comparing policies, review:
- Liability limits above Georgia's 25/50/25 minimum.
- Add-on versus reduced-by uninsured motorist coverage.
- Collision and comprehensive protection.
- Hail, flood, and glass provisions.
- Battery-related claims and exclusions.
- Tesla-approved collision repair facilities.
- Original parts, diagnostics, and camera calibration.
- Rental reimbursement and roadside assistance.
- Optional medical payments coverage.
- Charging equipment and accessories.
If your Model Y is financed or leased, your lender or leasing company may require collision and comprehensive insurance.
GAP protection may also be worth considering when the outstanding loan or lease balance could exceed the vehicle's insured value following a total loss. Compare equivalent coverage selections rather than choosing solely by the lowest advertised premium.
Frequently Asked Questions
What is the minimum Tesla Model Y insurance required in Georgia?
Georgia's standard automobile liability minimums are 25/50/25: $25,000 bodily injury per person, $50,000 bodily injury per accident, and $25,000 property damage per accident.
Is uninsured motorist coverage required in Georgia?
Georgia automobile liability policies generally include uninsured motorist coverage unless it is rejected in writing. Drivers can review add-on and reduced-by options, available limits, and the applicable selection requirements.
Does Georgia require full coverage on a Tesla Model Y?
Georgia generally does not require collision or comprehensive insurance by law for privately owned passenger vehicles. However, lenders and leasing companies may require both. "Full coverage" is not a standardized insurance policy.
Does insurance cover hail damage to a Tesla Model Y?
Comprehensive insurance generally covers eligible hail damage, subject to deductibles, exclusions, and policy terms. Liability-only insurance does not protect your own Model Y against hail damage.
Compare Tesla Model Y Insurance Options
Georgia Model Y owners should compare liability limits, uninsured motorist options, physical damage protection, battery-related claims, and Tesla-specific repair provisions before choosing an insurer. Understanding these differences can help you evaluate available insurance options more effectively.
About This Guide
SureEV provides general educational information and access to insurance comparison services. SureEV is not an insurance carrier and does not issue, underwrite, or bind policies. Coverage availability, eligibility, rates, and terms depend on the insurer and applicant. This guide is not personalized insurance advice.